No-deposit finance can look like the simplest route to a car, especially when cash is tight. The harder question is whether the offer remains manageable after interest, fees, insurance, and everyday running costs are included. Comparing lenders on the advertised instalment alone can hide important differences: one may quote a longer term, another may include a balloon payment, and a third may attach charges that change the total cost. A useful comparison turns each proposal into the same set of facts. This guide shows how to examine pricing, contract structure, affordability, and lender risk before choosing. The goal is not merely to find an approval, but to identify finance that fits your budget without creating avoidable pressure.
Put Every Offer on the Same Cost Sheet
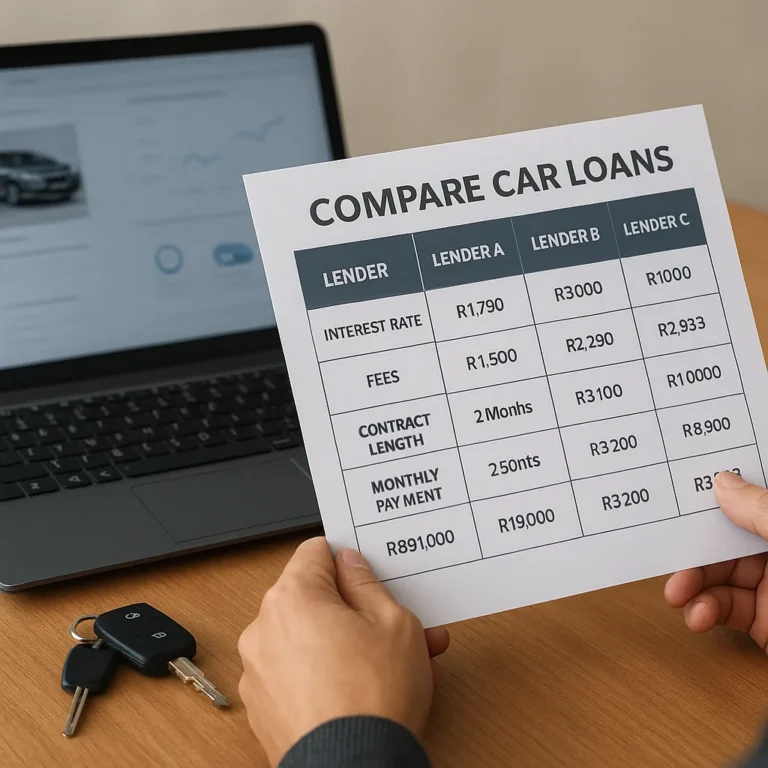
Start by recording the vehicle price, amount financed, interest rate, monthly instalment, term, initiation fee, monthly service fee, and any final balloon payment. Then ask whether registration, delivery, warranties, or accessories are included or financed. Comparing these items in separate adverts is misleading because a lower instalment may simply reflect a longer agreement or a larger final amount. Request a written quotation or pre-agreement statement showing the total amount payable. Keep the figures side by side, using the same vehicle and term where possible. This simple worksheet makes it easier to spot an offer that looks affordable only because key costs are less visible.
Look Beyond the Advertised Interest Rate
Interest is only one part of the price. Check whether the quote uses a fixed or variable rate, how interest is calculated, and whether the instalment can change. A longer term may reduce the payment but increase total interest and leave you owing more than the car is worth for longer. Ask about early settlement, missed-payment charges, insurance requirements, and consequences of default. If a balloon payment is proposed, calculate how you would fund it rather than assuming refinancing will be available. Compare total payable and contract risks together; a slightly higher instalment can be safer if it removes a large final obligation or expensive conditions.
Test the Payment Against Your Real Budget
Affordability should be tested against your real month, not a lender’s maximum. List take-home income, rent, food, utilities, existing credit, fuel, maintenance, insurance, and a reserve for irregular expenses. Add the proposed instalment and test the budget against a weaker month if your income varies. Consider whether the car payment would still work after a fuel-price increase or an unexpected repair. A lender may approve an amount that leaves little room for change because approval is not a personal financial recommendation. Use your own comfort limit and preserve an emergency buffer before treating any quote as suitable.
Assess the Risks Attached to the Agreement
Risk is not limited to the interest rate. A vehicle financed at its full price can start with little equity, so selling or replacing it early may leave a shortfall. Depreciation, accident damage, missed instalments, and added insurance costs can all affect that position. Ask who owns the vehicle during the agreement, what happens after a total loss, and whether comprehensive insurance is compulsory. Read the sections on repossession, arrears, and credit reporting before signing. If a broker presents several choices, confirm which lenders are being considered and how the broker is paid. Transparency matters when the cheapest-looking option carries the greatest downside.
Ask Final Questions Before You Choose
Before choosing, ask each lender the same final questions: What is the total amount payable? Which fees are compulsory? Can the rate or instalment change? Is there a balloon payment? What insurance and settlement rules apply? Check the provider through the National Credit Regulator and avoid paying an upfront fee to anyone promising guaranteed approval. Keep copies of adverts, quotations, messages, and the signed agreement. If the numbers do not make sense, pause and seek independent guidance. The strongest offer is the one you can understand, afford through ordinary setbacks, and repay without relying on a future raise or a new loan.
Where to continue your research safely
To keep researching, review National Credit Regulator and compare which option makes the most sense for your situation.
Key criteria to compare before you decide
A good decision depends on more than a first impression. Compare total cost, timing, reputation, effort required, and the clarity of the offer conditions. When those criteria are visible together, it becomes easier to tell whether an option solves the problem or only looks attractive at first.
How to use this guide for your next step
Review the criteria before moving forward
How should you compare no-deposit car finance offers before choosing a lender calls for context, comparison, and patience. Use the points above as a practical checklist: revisit your goal, look for concrete signals, and move forward only when the choice fits your current needs.